The contractor is booked, the materials are picked out, and you’re ready to see your renovation take shape. Between comparing quotes and deciding where everything will go, it’s easy to overlook one more conversation you should have before work begins.
Home insurance and renovations go together. Before work begins, tell your insurance broker what you have planned. Then they can review how the changes may affect your policy and explain any additional protection you may need during construction and after the project is complete.
That conversation gives you a chance to ask questions and understand your options before the renovation is underway.
Why Renovations Can Affect Your Home Insurance
Your home insurance policy reflects details about your home, including its size, construction, and finishes. Adding living space or upgrading materials can increase the amount it would cost to rebuild after a major loss. That rebuilding cost may be different from your home’s selling price or the property value used to calculate your taxes.
Think of an unfinished basement that becomes a family room with a bathroom and custom cabinetry. The house may look the same from the street, but there is more inside to replace after a major loss.
The work itself deserves a separate discussion. Ask your broker to review both stages of the project rather than focusing only on the finished result.
Home Renovations to Discuss With Your Broker
You don’t need to know which insurance terms apply before making the call. Start by describing what you plan to change.
Additions and Interior Renovations
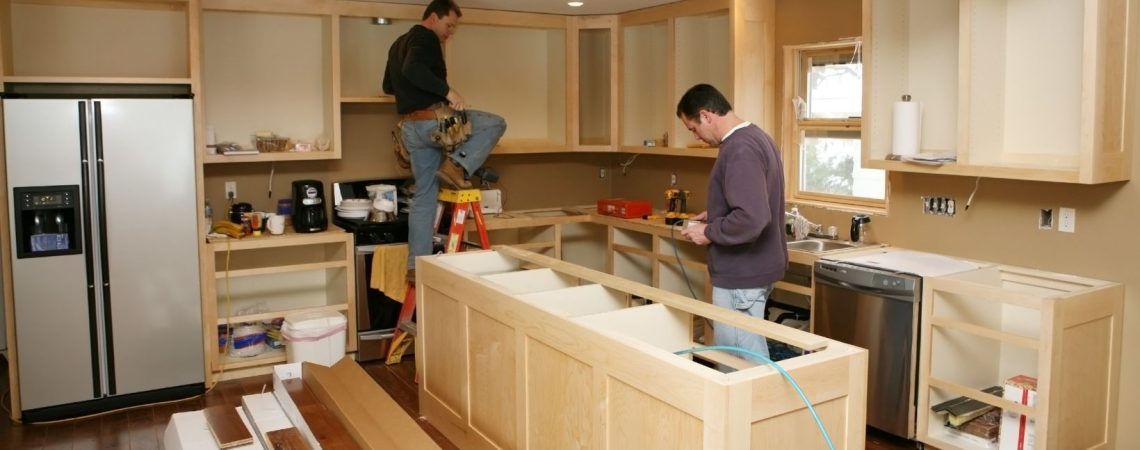
Discuss projects such as adding a bedroom, finishing a basement, removing walls, or extensively remodelling a kitchen. Share drawings or a written scope of work if you have them.
Be specific about what “renovating” means. Replacing cabinet handles is a different project from removing the kitchen, relocating plumbing, and opening a wall into the dining room.
Updates to Major Systems
A new roof, updated wiring, or replacement plumbing can change how your insurer assesses your home. Let your broker know what you are upgrading so your policy information reflects those improvements.
Keep invoices and details about the completed work, including when it was done and who completed it. These records help us provide accurate information to your insurer and review how the updates may affect your coverage.
Changes to How You Use Your Home
Tell your broker if your renovation includes creating a rental suite or space for a home business. How you plan to use the finished space can affect the coverage you need.
A basement bedroom for visiting family raises different insurance considerations than an apartment for tenants. Similarly, a home office where you work alone is different from a space where customers visit. Sharing these details helps us identify what needs to be reviewed before the space is put to use.
What to Tell Your Broker Before Work Begins
Have the following details ready to make the discussion easier.
- A description of the renovation and its estimated cost.
- The expected start and completion dates.
- Structural changes or updates to major systems.
- Your contractor’s details and available proof of insurance.
- Whether you will stay in the home throughout the project.
- Any planned interruptions to heating, water, or electricity.
- How the renovated space will be used.
Ask what documents are needed and request confirmation of any coverage changes. Keep that information with your renovation records so it is easy to find.
Confirm Your Coverage During Construction
Additional Protection for the Project
Depending on the renovation, your insurer may require changes to your policy or additional construction coverage. Builder’s risk insurance can protect the structure and building materials against covered losses during the work.
Your contractor’s liability policy serves a different purpose and shouldn’t be assumed to insure the entire project. Ask your broker who is arranging construction coverage and what it includes.
Leaving the Home During Renovations
If you plan to stay elsewhere, explain the arrangement before moving out. Policies can have conditions or exclusions involving vacant or unoccupied properties during construction.
Ask how your insurer will treat the absence and what requirements apply. Don’t assume that regular contractor visits satisfy every occupancy condition.
Why Keeping Your Insurer Updated Matters
Your insurance needs can change before your next renewal. Keeping your broker informed throughout a renovation helps ensure your insurer has an accurate picture of the property and the work underway.
An unreported significant change could affect coverage if you need to make a claim. The outcome depends on your policy and the circumstances. If the project grows, the completion date shifts, or you decide to move out during construction, let them know so they can review what those changes mean for your protection.
Review Your Policy When the Work Is Finished
Before putting away the renovation paperwork, let your broker know the project is complete. Offer photographs, invoices, and a summary of any differences between the original plan and the finished work.
Ask to review the rebuilding estimate, relevant coverage limits, and any temporary construction arrangements. It’s a useful final step alongside the contractor walkthrough.
Talk to Will Marshall Before Your Renovation Begins
A renovation should leave you with a home that works better for your life. Taking time to review your insurance helps you understand how to protect the investment you are making.
Will Marshall Insurance Brokers serves homeowners in Barrie, Orillia, and surrounding communities. Our team can discuss your plans, explain your options, and help you review coverage as your home changes.
Contact Will Marshall Insurance Brokers before work begins to discuss your renovation and get clear answers about your home insurance.
Frequently Asked Questions
Do I Need to Report Painting or Small Cosmetic Updates?
Minor cosmetic work may not require coverage changes. If your project goes beyond surface updates, or you are unsure what your policy requires, check with your broker.
Will Renovations Always Increase My Premium?
No. The effect depends on the work and the insurer’s assessment. Ask for an explanation of any price change and the coverage it reflects.
Do I Need to Report Renovations I Am Doing Myself?
Yes. Describe the planned work even if you are completing it yourself. Hiring a contractor isn’t the only reason a renovation may need an insurance review.
What if the Renovation Has Already Started?
Contact your broker promptly. Explain what has been completed and what remains, then ask what needs to happen next.